Key Takeaways
- Amaero’s U.S. IPO, originally slated to raise ≈ $52.6 M by selling 7.46 M shares at $7.06 each, has been postponed due to “unfavorable market conditions.”
- The company’s SEC registration remains active, but no new offering date has been announced.
- Amaero’s Tennessee plant currently produces ≈ 680 t/yr of spherical refractory and titanium‑alloy powders; a fourth EIGA atomizer slated for June 2027 will lift capacity to ≈ 920 t/yr.
- Total capital deployed to date: $48.3 M (through 30 Jun 2026); an additional $16.5 M is earmarked for the final build‑out.
- The IPO proceeds were intended to fund the remaining $16.5 M expansion and to provide working‑capital flexibility for U.S. market penetration.
Background: The Deferred Nasdaq Listing
Amaero, a specialist in high‑purity metal powders for additive manufacturing (AM) and powder‑metallurgy hot‑isostatic pressing (PM‑HIP), filed a Form S‑1 with the U.S. Securities and Exchange Commission in September 2026. The prospectus outlined an offering of roughly 7.5 million shares on the Nasdaq Global Select Market under the ticker AMRO. At the prospectus price of $7.06 per share, the gross proceeds would have been $52.6 million.
On 24 Sep 2026, the company announced a postponement, citing “adverse market conditions.” The registration statement remains on file, but the SEC has not yet declared it effective, and Amaero has not disclosed a revised timetable.
Expansion Strategy: Powder Production in Tennessee
Current Facility Footprint
Location: McDonald, Tennessee
Core technologies:
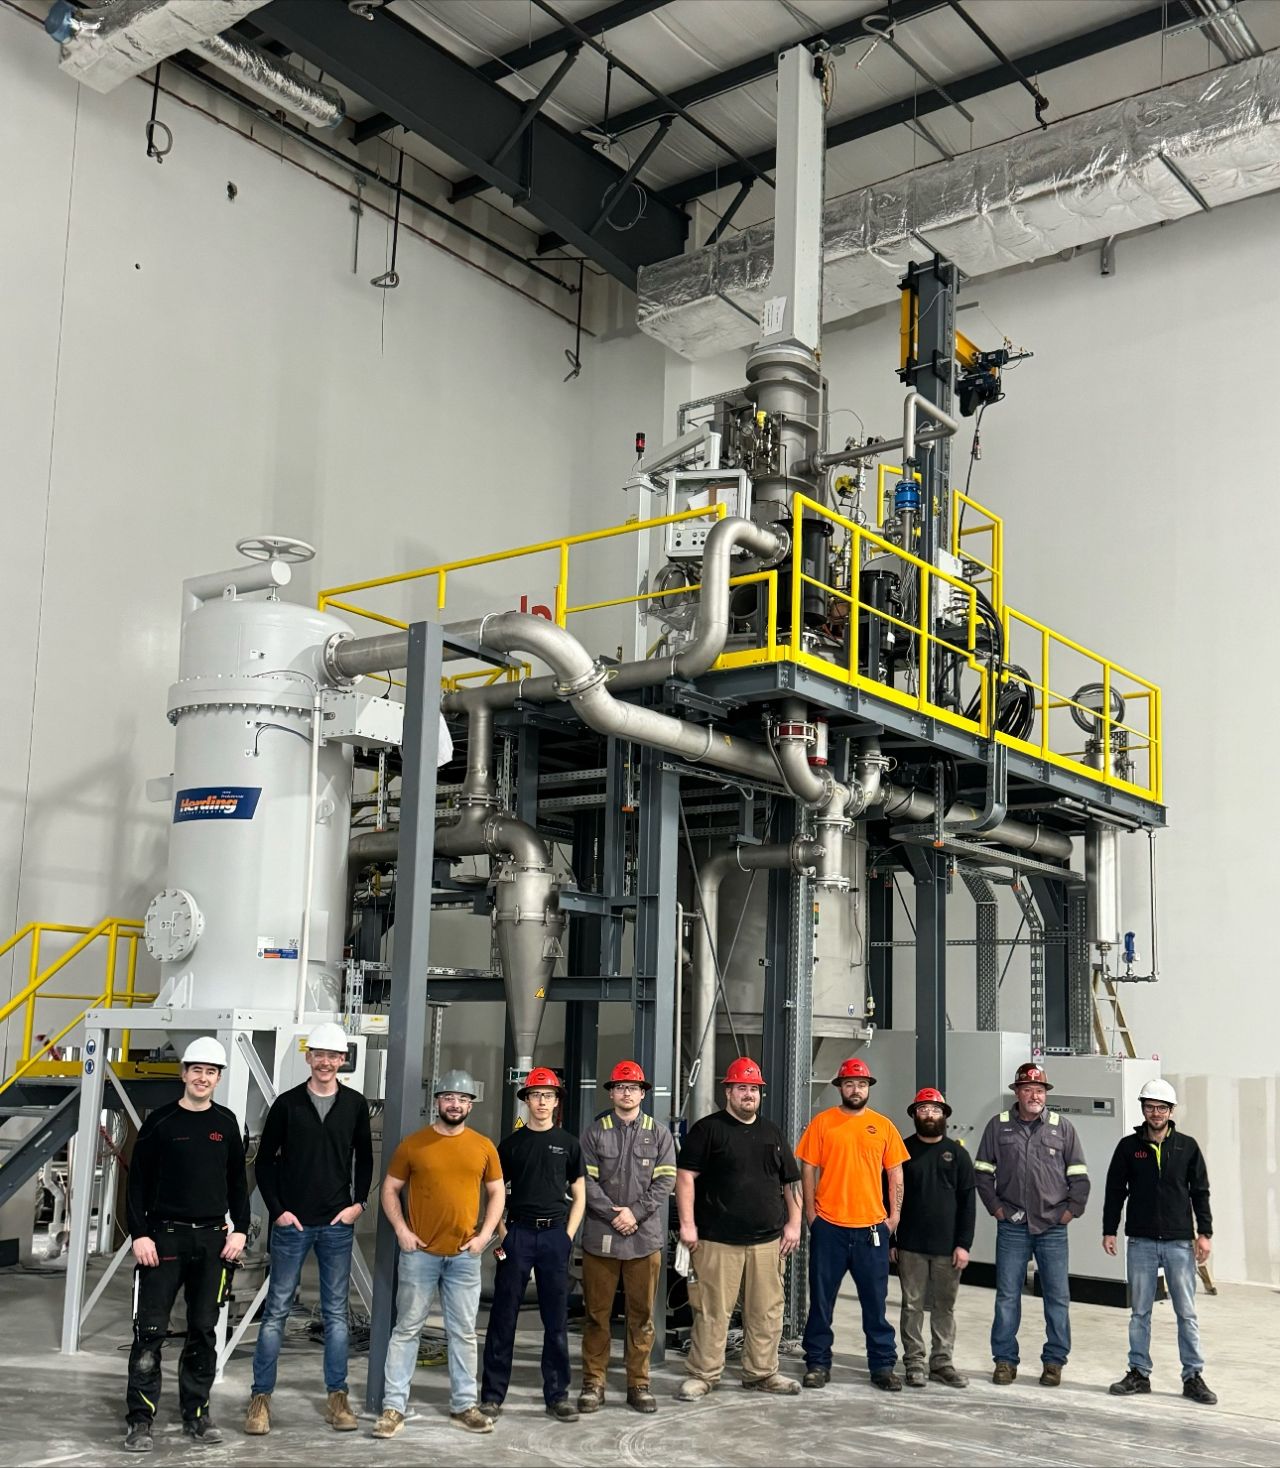
- Electrode Induction Melting Inert Gas Atomization (EIGA) – three units in operation (the third commissioned Jun 2026).
- PM‑HIP for large‑scale component consolidation.
Annual output (2026): ≈ 680 metric tons of spherical refractory and titanium‑alloy powders.
Planned Capacity Boost
| Metric | Today (2026) | After 4th EIGA (Jun 2027) |
|---|---|---|
| EIGA units | 3 | 4 |
| Powder capacity | 680 t/yr | 920 t/yr |
| Additional capital required | – | $16.5 M |
| Key spend items | – | $3.3 M (4th EIGA) $2.2 M (argon‑gas recycling) $11 M (processing & PM‑HIP equipment) |
The fourth atomizer is projected to increase throughput by ≈ 35 %, positioning Amaero to meet rising demand from aerospace, defense, and high‑performance automotive sectors that rely on AM‑compatible powders.
Financial Commitment to U.S. Build‑Out
- Capital already invested (through 30 Jun 2026): $48.3 M in land, buildings, and primary equipment.
- Future outlays (projected): $16.5 M, broken down as follows:
| Category | Amount (US$) |
|---|---|
| Fourth EIGA system | 3.3 M |
| Argon‑gas recycling loop | 2.2 M |
| Powder‑processing & PM‑HIP hardware | 11 M |
| Facility upgrades & contingency | — |
These expenditures are expected to be funded largely by the IPO proceeds, supplemented by existing cash reserves and potential debt facilities.
Market Context
The global metal‑powder market is forecast to reach $13.2 B by 2030, growing at a CAGR of 9.4 % (Source: MarketsandMarkets, 2025). U.S. demand is accelerating due to defense‑grade AM programs and the Federal Aviation Administration’s push for lightweight titanium components. Amaero’s focus on spherical, low‑oxygen powders aligns with the stringent specifications of aerospace OEMs, giving it a competitive edge over legacy gas‑atomized producers that typically deliver higher impurity levels.
Comparison: EIGA vs. Conventional Gas Atomization
| Attribute | EIGA (Amaero) | Conventional Gas Atomization |
|---|---|---|
| Particle sphericity | > 99 % | 95‑98 % |
| Oxygen content | < 0.02 % | 0.03‑0.05 % |
| Energy efficiency | ~ 15 % lower specific energy consumption | Higher |
| Production flexibility | Rapid alloy changeover (≤ 48 h) | Longer changeover (≥ 72 h) |
| Capital cost (per unit) | $8‑9 M | $6‑7 M (lower upfront, higher operating cost) |
The superior particle quality of EIGA reduces downstream processing time and improves part‑density in AM builds, justifying the higher capital outlay.
Outlook
While the IPO delay adds uncertainty to Amaero’s near‑term liquidity, the company’s capital‑intensive expansion is already well‑funded through internal cash flow and prior financing rounds. Completion of the fourth EIGA system will unlock ~ 240 t/yr of additional capacity, enabling Amaero to capture a larger share of the fast‑growing U.S. metal‑powder market.
Bottom Line
Amaero’s decision to postpone its $52.6 M Nasdaq debut reflects short‑term market volatility rather than a shift in strategic direction. The firm remains on track to finish a $16.5 M expansion that will lift annual powder output from 680 t to 920 t, a 35 % increase powered by a fourth EIGA atomizer. With a solid capital base and technology that delivers ultra‑pure, spherical powders, Amaero is positioned to meet escalating demand from aerospace, defense, and high‑performance manufacturing sectors. Investors should monitor the company’s next filing for a revised IPO schedule and any supplemental financing that may accompany the final build‑out.


