Key Takeaways
- Tekna’s FY‑2026 Q2 revenue jumped 61 % YoY to CAD 13.4 M (≈ US $9.5 M).
- Materials sales (powders & feedstock) generated CAD 8.6 M, up 20 % YoY.
- Systems revenue exploded 270 % YoY, reaching CAD 5.04 M (≈ US $3.6 M) and now represents > 35 % of total quarterly sales.
- Q3 saw a return to loss after a one‑off Asian consolidation charge, but the underlying growth trends remain bullish for metal‑additive‑manufacturing (AM).
- The dual‑division strategy—selling machines to lock‑in future powder demand—positions Tekna as a catalyst for the broader AM metals market.
1. Market Context: Metals vs. Plastics in Additive Manufacturing
Additive manufacturing continues to be split between two primary material families:
| Segment | Current Focus | Growth Driver | Typical Applications |
|---|---|---|---|
| Metal Powders | High‑value aerospace, defense, medical implants | Supply‑chain resilience, performance‑critical parts | Turbine blades, jet engine components, orthopedic implants |
| Polymer Filaments | Consumer goods, tooling | Cost‑effectiveness, design flexibility | Footwear midsoles, automotive prototypes |
While polymer AM enjoys broader adoption, metal powders remain the centerpiece of national strategies aimed at securing domestic manufacturing capabilities. The difficulty of re‑establishing high‑purity powder production lines makes metals the “strategic commodity” of the next decade.
2. Tekna’s Q2 Performance – A Profit Turnaround
Tekna, a Quebec‑based supplier majority‑owned by Norway’s Arendal Fossekompani, posted a modest profit in Q2 2026 after years of operating losses. The profit was driven primarily by:
- Revenue: CAD 13.4 M (US $9.5 M), +61 % YoY.
- Materials Division: CAD 8.6 M, +20 % YoY, accounting for ≈ 64 % of total revenue.
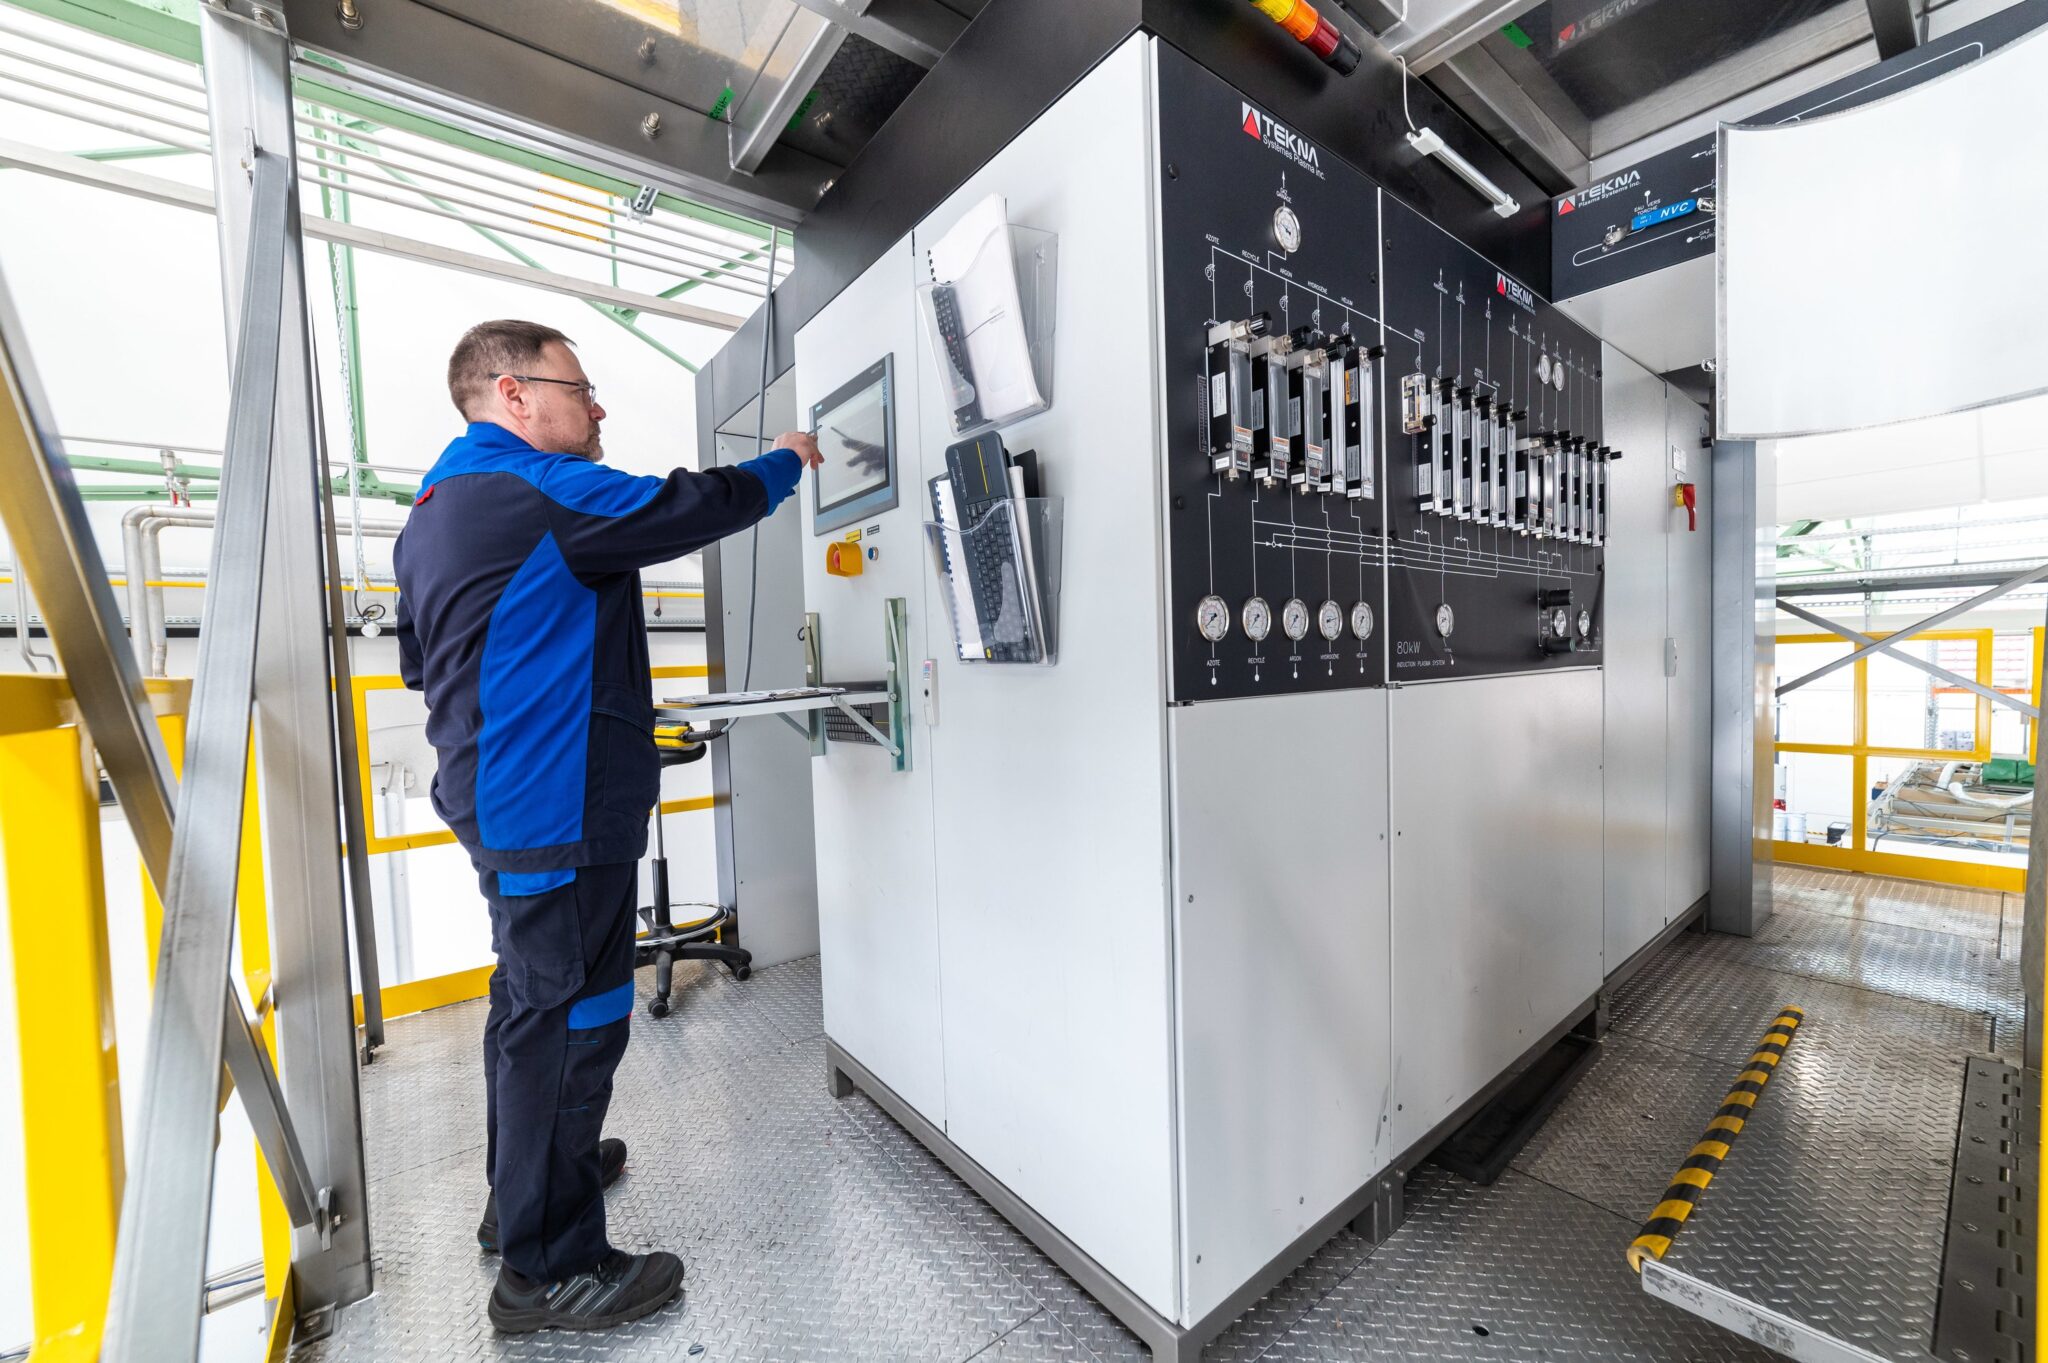
- Systems Division: CAD 5.04 M, +270 % YoY, now > 35 % of quarterly sales.
The surge in systems sales reflects heightened demand for turnkey AM solutions, especially from aerospace OEMs that prefer a single vendor for both hardware and consumables.
3. Q3 Setback – One‑Time Consolidation Costs
In Q3 2026 Tekna reverted to a net loss, not because of a slowdown in demand, but due to a non‑recurring expense linked to consolidating its Asian footprint:
| Metric | Q2 2026 | Q3 2026 |
|---|---|---|
| Revenue | CAD 13.4 M | CAD 12.7 M (‑5 %) |
| Net Income | +CAD 0.6 M | –CAD 0.9 M |
| Consolidation Charge | – | CAD 1.2 M |
The dip in top‑line revenue is marginal (≈ 5 %). The core growth engines—materials and systems—remain on an upward trajectory, suggesting the loss is a short‑term accounting artifact rather than an operational weakness.
4. Why Systems Growth Matters More Than It Looks
The 270 % jump in systems revenue is not merely a sales spike; it is a strategic lever:
- Customer Lock‑In: Each machine sold typically guarantees a multi‑year powder purchase agreement, boosting future material sales.
- Cross‑Sell Potential: Installation and service contracts create recurring revenue streams.
- Market Validation: OEMs are committing capital to AM, indicating confidence in metal‑part performance and cost‑parity projections.
Consequently, the systems division is a leading indicator for the health of the metal‑powders market.
5. Segment‑Specific Drivers
- Aerospace & Defense: Contracts for turbine‑blade and structural‑component printing drove the 20 % YoY rise in material sales.
- Medical: Increased demand for patient‑specific implants added a modest but steady boost.
- Geographic Expansion: The Asian consolidation aims to centralize logistics, reduce lead times, and improve margin visibility across the region.
Bottom Line
Tekna’s FY‑2026 Q2 results illustrate a pivotal shift from loss‑making to profitability, powered by explosive growth in its systems division and steady gains in high‑margin metal powders. Although Q3 recorded a one‑off loss due to Asian restructuring, the underlying revenue dynamics—61 % YoY total growth, 20 % YoY material growth, and 270 % YoY systems growth—signal a robust outlook for metal‑additive‑manufacturing. By coupling machine sales with powder contracts, Tekna is not only expanding its own topline but also accelerating the broader adoption of metal AM in aerospace, defense, and medical sectors.


