Key Takeaways
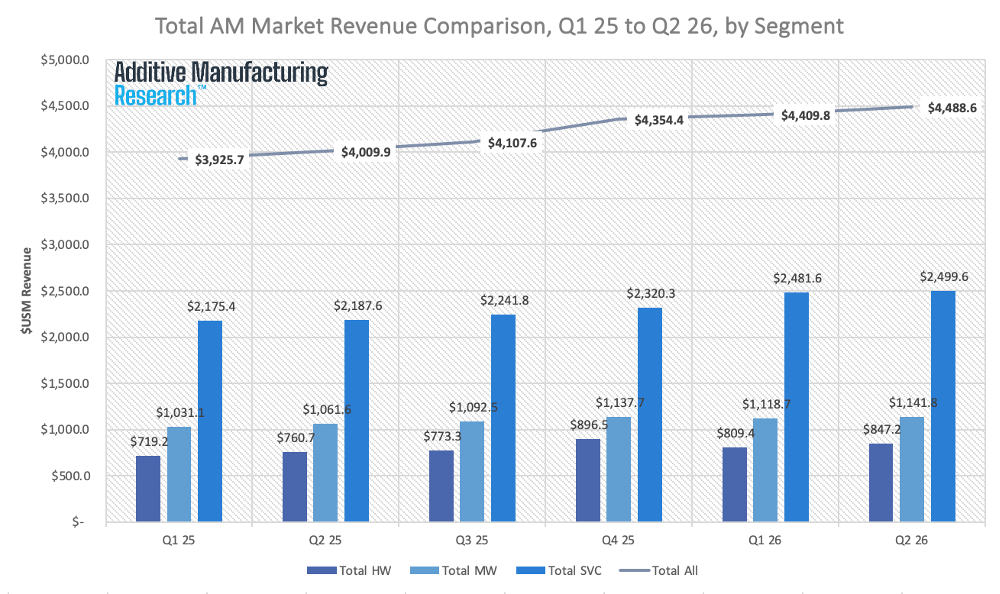
- Additive‑manufacturing (AM) services generated $2.5 B in Q2 2026, a 14 % YoY increase and more than 55 % of the total $4.48 B quarterly market.
- Metal AM revenue rose to $1.81 B (+14 % YoY); Polymer AM grew to $2.68 B (+11 % YoY).
- Outsourcing to service bureaus lets companies avoid the $500 K‑$2 M capital outlay for industrial printers, a trend that is accelerating as firms tighten CapEx budgets.
- Industry analysts warn that rising interest rates could dampen future investment, potentially slowing the current growth momentum.
The Service‑Driven Upswing in Additive Manufacturing
Revenue Snapshot – Q2 2026
Additive Manufacturing Research (AM Research) released its Q2 2026 3DP/AM Market Data and Forecast and the companion 3DP/AM Market Insights report. The data show a clear shift: while the overall AM market expanded 12 % YoY, the services segment outpaced it with a 14 % increase, moving from $2.19 B in Q2 2025 to $2.50 B in Q2 2026.
Metal vs. Polymer – Where the Money Is Going
| Segment | Q2 2025 Revenue | Q2 2026 Revenue | YoY Growth |
|---|---|---|---|
| Metal AM (all) | $1.59 B | $1.81 B | +14 % |
| Polymer AM (all) | $2.42 B | $2.68 B | +11 % |
| Combined Services | $2.19 B | $2.50 B | +14 % |
| Total AM Market | $4.01 B | $4.48 B | +12 % |
Sources: AM Research Q2 2026 market data.
Why Services Are Outpacing Hardware Sales
- Capital efficiency – Purchasing a production‑grade metal printer can cost $500 K to $2 M, plus ongoing maintenance and material handling infrastructure. Service bureaus absorb these expenses, offering “pay‑as‑you‑go” pricing.
- Speed to market – Companies can prototype or launch low‑volume parts within days, leveraging the provider’s existing material libraries and certified process qualifications.
- Risk mitigation – Outsourcing sidesteps the steep learning curve associated with process qualification, certification, and quality‑control documentation required for in‑house AM.
These advantages are especially compelling in a macro environment where interest rates have risen to 5.8 %, tightening corporate CapEx budgets.
Analyst Perspective
Scott Dunham, Executive Vice President at AM Research, highlighted that the first half of 2026 delivered “robust growth for many as forecasted,” with capital returning to the sector after a brief lull. However, he cautioned that further rate hikes could pressure future CapEx, potentially curbing the rapid expansion of both hardware purchases and service contracts.
Implications for Manufacturers and Suppliers
- Service bureaus are becoming the primary gateway to AM for midsize and large enterprises, positioning them as strategic partners rather than mere vendors.
- Equipment manufacturers must pivot toward offering managed‑service packages, software ecosystems, and post‑processing solutions to stay relevant.
- Investors should monitor the service‑revenue share (now >55 % of total AM) as a leading indicator of market health, especially in periods of monetary tightening.
Bottom Line
Additive‑manufacturing services have solidified their role as the growth engine of the sector, delivering $2.5 B in Q2 2026 revenue—a 14 % year‑over‑year rise that eclipses overall market growth. By allowing firms to bypass the high upfront costs of industrial printers, service providers are capturing the majority of new spending. While the outlook remains positive, escalating interest rates could temper future capital allocations, making the service model even more critical for sustaining momentum in the AM landscape.


