Key Takeaways
- IPO target: $52.6 million by selling ~7.5 M shares at $7.06 each on the Nasdaq Global Select Market (ticker AMRO).
- Current capacity: 680 t/yr of spherical refractory & titanium-alloy powders at the McDonald, TN plant.
- Planned capacity: 920 t/yr after the fourth EIGA atomizer becomes operational (June 2027).
- Capital outlay: $48.3 M already invested in U.S. facilities; an additional $16.5 M required to finish the build-out.
- Proceeds allocation: Up to $17.5 M earmarked for new equipment; the balance will fund working capital, R&D, and general corporate needs.
Overview of Amaero’s U.S. IPO
Amaero, a specialist in high-purity metal powders for additive manufacturing (AM) and powder-metallurgy hot isostatic pressing (PM-HIP), filed a registration statement with the U.S. Securities and Exchange Commission (SEC) to raise roughly $52.6 million. The company intends to list on the Nasdaq Global Select Market under the ticker AMRO. The filing (Form S-1) proposes an offering of 7.5 million shares priced at $7.06 per share, though the final amount may shift with market conditions.
“The offering will provide the liquidity needed to complete our strategic expansion of U.S. manufacturing capacity,” the prospectus states.
U.S. Manufacturing Expansion in Tennessee
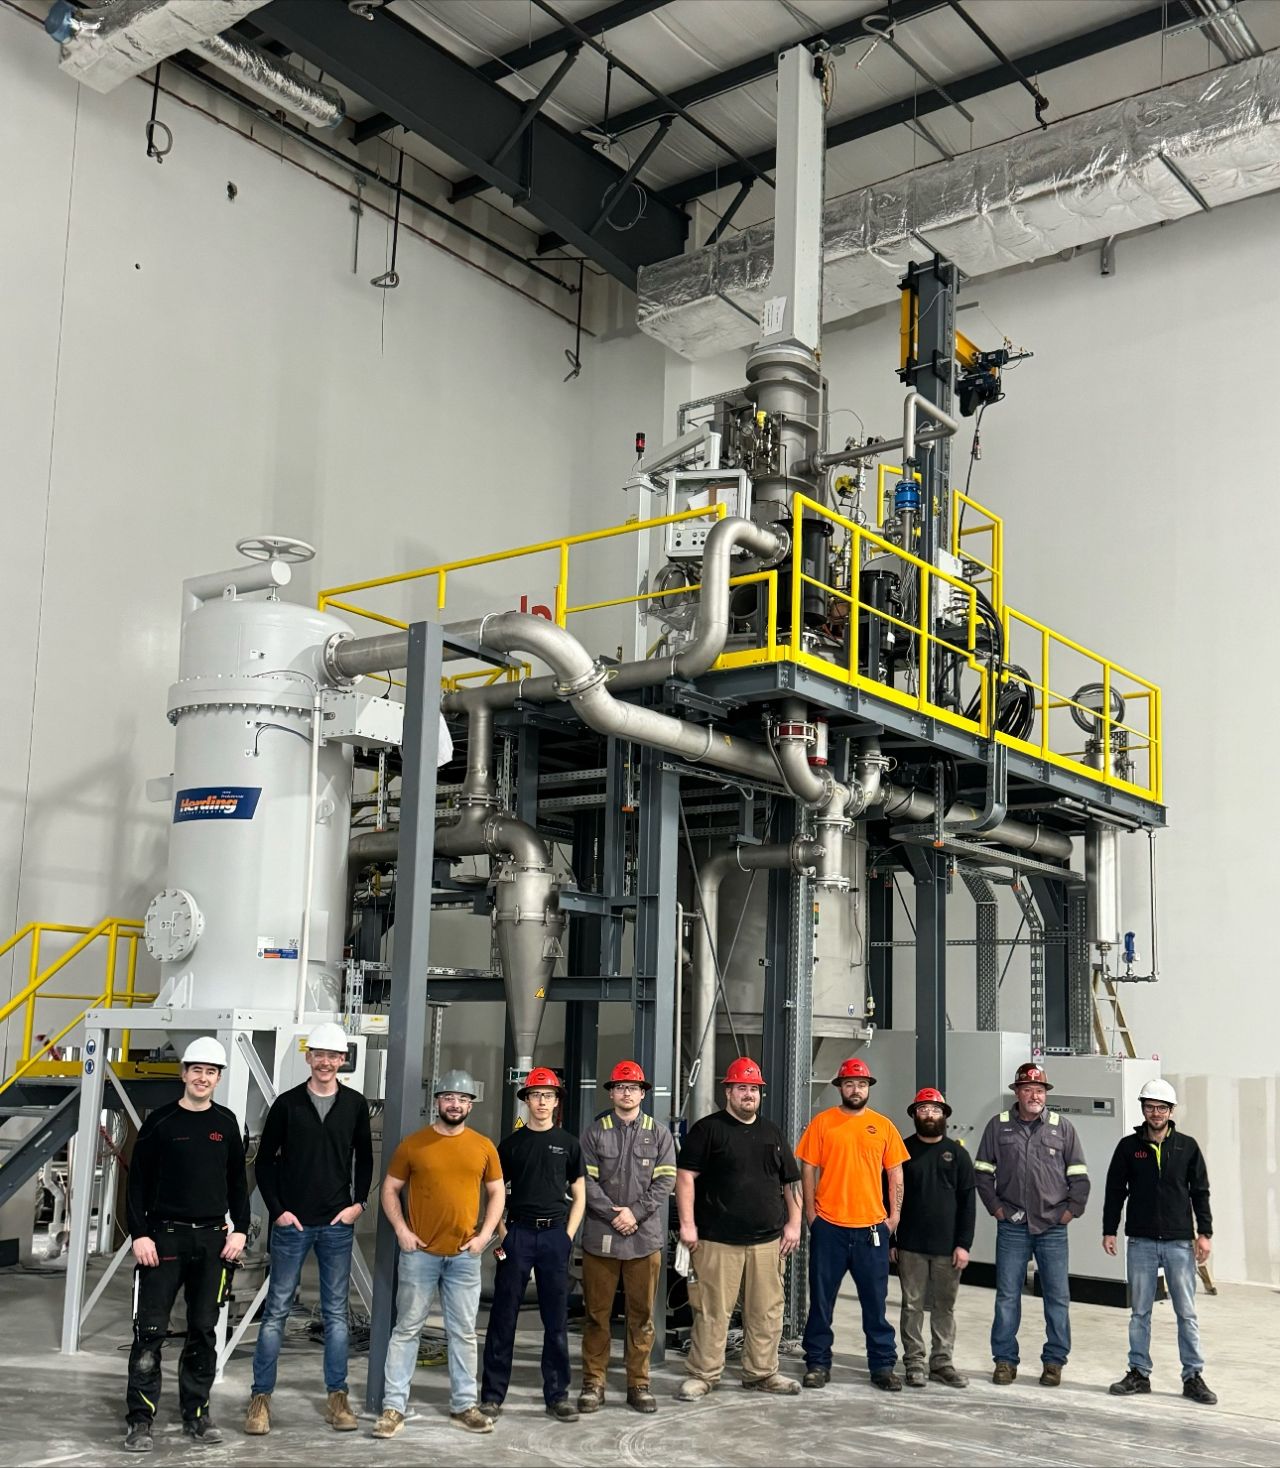
Amaero’s sole U.S. plant sits in McDonald, Tennessee, where it runs three Electrode Induction Melting Inert Gas Atomization (EIGA) systems. The third unit entered service in June 2026; a fourth is slated for June 2027.
- Current equipment: 3 EIGA atomizers, dedicated argon-recycling loop, and PM-HIP furnaces.
- Future equipment: 4th EIGA, upgraded argon recovery, and expanded powder-handling lines.
The company has already poured $48.3 M into property, plant, and equipment (PP&E) through the first half of 2026. An additional $16.5 M is projected to finish the build-out, broken down as follows:
| Item | Approx. Cost (USD) |
|---|---|
| Fourth EIGA system | $3.3 M |
| Argon gas recycling upgrade | $2.2 M |
| Powder processing & PM-HIP equipment | $11.0 M |
| Facility improvements (misc.) | — |
| Total additional spend | $16.5 M |
Production Capacity Outlook
The Tennessee site presently churns ~680 metric tons of metal powder per year. Once the fourth atomizer is online, capacity will climb to ~920 t/yr, representing a 35 % increase. This scale-up positions Amaero to meet rising demand from aerospace, defense, and medical-device manufacturers that rely on high-performance AM feedstock.
| Metric | Current (2026) | Post-buildout (2027) |
|---|---|---|
| Powder output | 680 t/yr | 920 t/yr |
| Number of EIGA units | 3 | 4 |
| Argon recycle efficiency* | 85 % | 92 % |
| Capital invested (cumulative) | $48.3 M | $64.8 M |
*Efficiency measured as the percentage of argon recovered and reused in the atomization process.
Allocation of IPO Proceeds
Amaero disclosed a disciplined use-of-proceeds plan:
| Use | Approx. Allocation |
|---|---|
| Capital equipment (new EIGA, HIP, processing lines) | $17.5 M |
| Working capital & operating expenses | $20-$25 M |
| Research & development (powder alloy development, process optimization) | $5-$7 M |
| General corporate purposes (legal, compliance, marketing) | Remainder |
The equipment budget aligns with the $16.5 M build-out estimate, leaving a modest buffer for unforeseen costs and strategic initiatives.
Why the IPO Matters for the Metal-Powder Market
- Liquidity for growth: The capital raise will accelerate Amaero’s ability to capture a larger share of the U.S. AM powder market, projected to exceed $5 B by 2030.
- Supply-chain resilience: Domestic production reduces reliance on overseas powder sources, a critical factor for defense contracts that require “Made-in-USA” certification.
- Technology edge: EIGA atomization delivers tighter particle-size distributions and lower oxygen content (<0.02 wt % O₂) than conventional gas-atomized powders, translating to superior mechanical properties in printed parts.
Bottom Line
Amaero’s $52.6 million Nasdaq debut is a strategic financing move that underwrites a 35 % capacity boost at its Tennessee facility, bringing annual metal-powder output to ~920 t. With $48.3 M already invested and a further $16.5 M earmarked for equipment, the company is poised to meet escalating demand from high-value additive-manufacturing sectors while strengthening U.S. supply-chain security. The IPO not only supplies the cash needed for the build-out but also positions AMRO as a publicly traded benchmark for next-generation metal-powder producers.


